Table of Contents
Your contents policy might protect a sofa at home but not while you carry it downstairs. Renovating before moving adds a separate set of risks. A rented truck brings another contract again.
These DIY moving insurance gaps in Sydney can leave expensive losses on your own bill. A $10,000 loss is an example, not a typical claim or promised outcome. Check each policy before lifting the first box.
This guide separates renovation, transit, vehicle and storage cover. Every insurer sets its own terms. Only your current policy and written insurer advice can confirm your protection.
The $50,000 Renovation Threshold Limit
There is no universal Australian home insurance rule that stops cover at $50,000 of renovations. Insurers may use different project values, work types and notification rules. Ask yours what applies before work begins.
A move and a renovation are different jobs. Ordinary contents insurance may address household belongings. Renovation cover may address works, materials and risks created by builders or owner-builders.
The Cost Gap ($20,000–$100,000+)
A failed kitchen rebuild or major water leak could create a five-figure repair bill. The $20,000–$100,000+ heading shows a possible exposure, not a published Australian average. Your actual loss depends on the damage and contract.
List your project value, open roof or wall work, and site security. Ask the insurer which events remain covered. Get the answer in writing before any contractor starts.
The Valuation Trap
The trap is valuing only materials while forgetting paid labour and other work. Insurers may ask for the full project scope. NSW owner-builder permit rules use reasonable market costs for labour and materials.
Check the NSW owner-builder guidance before planning structural work. It explains when an owner-builder permit is required. That legal test does not set your home insurer’s renovation limit.
Directly Comparing Standard vs. Required Renovator Policies
A standard home policy and specialist renovation cover can protect different things. There is no single renovator policy required for every NSW project. Ask your insurer and contractor which risks each policy handles.
Project value over $50,000
Ask whether a $50,000 project changes your cover, excess or duty to notify. Do not assume a new policy starts automatically. Give the insurer the full scope before contracts are signed.
Water damage from open roofs/walls
An uncovered roof can let rain reach ceilings, wiring and boxed furniture. Policies may treat water entering during building work differently. Confirm temporary weatherproofing, accidental damage and any workmanship exclusions.
Injuries to friends / site visitors
A friend helping with paintwork may face different risks from a guest carrying boxes. Ask about legal liability, workers compensation duties and volunteer help. Keep people away from active work zones.
Theft of building materials onsite
New flooring, tools and bathroom fittings may not count as household contents. Ask about theft from sheds, open sites and unlocked garages. Confirm who insures materials before installation.
Exceeding the Uninsured Renovation Limit
Your policy could change if the project exceeds a declared value or approved scope. This is a contract issue, not a universal dollar limit. Notify your insurer when the plan changes.
The Gap
An extra bathroom or wall removal can change building risk overnight. The original disclosure may no longer describe the work. Ask for an updated schedule or written confirmation of unchanged cover.
The $10K+ Hit
Imagine a water leak ruins $12,000 of newly installed cabinetry. That is an illustrative loss, not a forecast. If an exclusion applies, you may have to fund repairs yourself.
The “Faulty Workmanship” Blind Spot
Insurance may cover some resulting damage without paying to redo defective work. The answer depends on the event, wording and cause. A contractor warranty is not the same as home insurance.
The Gap
Suppose faulty plumbing leaks into a completed room. Replacing the pipe and repairing water damage may be treated differently. Ask the insurer and contractor about both costs.
The $10K+ Hit
A failed shower installation could require removing tiles, treating damp and rebuilding a room. Those costs might exceed $10,000. Do not treat that illustration as a standard claim amount.
Unlicensed Electrical and Plumbing Works
DIY electrical, plumbing and gas work can create safety and insurance problems. An NSW owner-builder permit does not authorise specialist licensed work. Use properly licensed tradespeople for those tasks.
The Cost Gap ($15,000–$50,000+)
A wiring fire or plumbing leak could damage a kitchen, wall cavity or adjoining unit. The displayed range is illustrative only. Ask tradespeople for licence details, a written scope and insurance information.
Take photos before walls are closed. Keep invoices and compliance paperwork where applicable. A clear record helps explain who performed each task.
Unapproved Structural Changes (DA / CDC Violations)
Moving house does not give you permission to alter structural walls. Some minor works qualify as exempt development. Other work may need a development application or complying development certificate.
The Cost Gap ($30,000–$100,000+)
A failed alteration may require engineering advice, support work and rebuilding. Costs depend on the property and problem. Do not rely on this heading’s figures as council fees or typical repairs.
Check your council and the NSW Planning Portal before changing load-bearing elements. An approval problem and an insurance exclusion are separate questions. Both deserve checking early.
The Council Penalty & Retrospective Approval Trap
Unauthorised work can lead to council action and requests for further evidence. Retrospective approval is not guaranteed. Speak with the council or a qualified certifier before altering a property.
The Gap
Insurance cannot replace the correct building approval. A policy payout also cannot make unsafe work lawful. Keep the scope, plans and approvals together during your move.
The $10K+ Hit
An order to investigate or reverse unsafe work could create a large personal expense. The outcome varies by project. No fixed $10,000 council penalty applies to every approval breach.
The 60-Day “Unoccupied House” Penalty
There is no universal 60-day penalty across Australian home policies. Some insurers apply extra conditions after a specified vacancy period. Others use different periods, excesses or definitions of occupancy.
The Cost Gap ($10,000+)
A vacant Sydney home can still suffer a break-in, burst pipe or storm damage. A claim might exceed $10,000, but the policy determines payment. Tell both old and new insurers your exact moving dates.
Ask how overnight stays, renovations and regular inspections affect the definition of unoccupied. Obtain written approval if you will leave either property empty.
Did you know?
Some contents policies offer moving-home benefits, but they can have limits and exclusions. Check the actual product disclosure statement before assuming transit or storage is covered.
Third-Party Site Injuries & Public Liability
A visitor injury during renovation can raise legal liability questions. Ordinary home liability cover may not extend to every building activity. Contractor public liability insurance addresses different risks again.
The Cost Gap ($10,000–$1,000,000+)
Serious injury claims can be costly, but no single payout range fits every incident. Ask who is covered during building work. Keep uninsured helpers away from ladders, exposed wiring and demolition areas.
Removalist public liability insurance is not the same as insurance for your possessions. Ask a company for its current insurance details. Confirm any goods cover separately.
The Goods-in-Transit Insurance Gap
Goods-in-transit insurance concerns belongings travelling between locations. It is separate from the truck’s vehicle policy. Compare your home contents cover, any transit policy and the removalist’s terms.
Contents Between Homes
Does home insurance cover moving house? Sometimes, but only within the stated limits. The MoneySmart contents insurance guide recommends checking moving benefits and policy exclusions. Ask about both addresses and the trip between them.
Loading and Unloading Cover
A mirror can break on the stairs before it reaches the truck. Another may fall during unloading. Ask exactly when transit cover starts and stops, including any self-packing conditions.
Theft During Transit
Theft cover may depend on locking, supervision and parking requirements. A truck left overnight creates another exposure. Confirm theft conditions before you choose the route or stop.
Accidental Transit Damage
Braking can shift an unsecured fridge, piano or dining table. Check whether accidental damage is insured and how fragile items must be packed. Professional loading does not automatically create an insurance policy.
If DIY handling feels risky, speak with furniture removalists in Sydney about handling and transport. Ask for written insurance details before booking any company.
Rental Truck Cover Does Not Cover Everything
Rental vehicle insurance usually concerns damage to the vehicle under its hire agreement. It does not automatically protect your sofa, television or boxed possessions. Read both contracts before collecting keys.
Vehicle Cover vs Cargo Cover
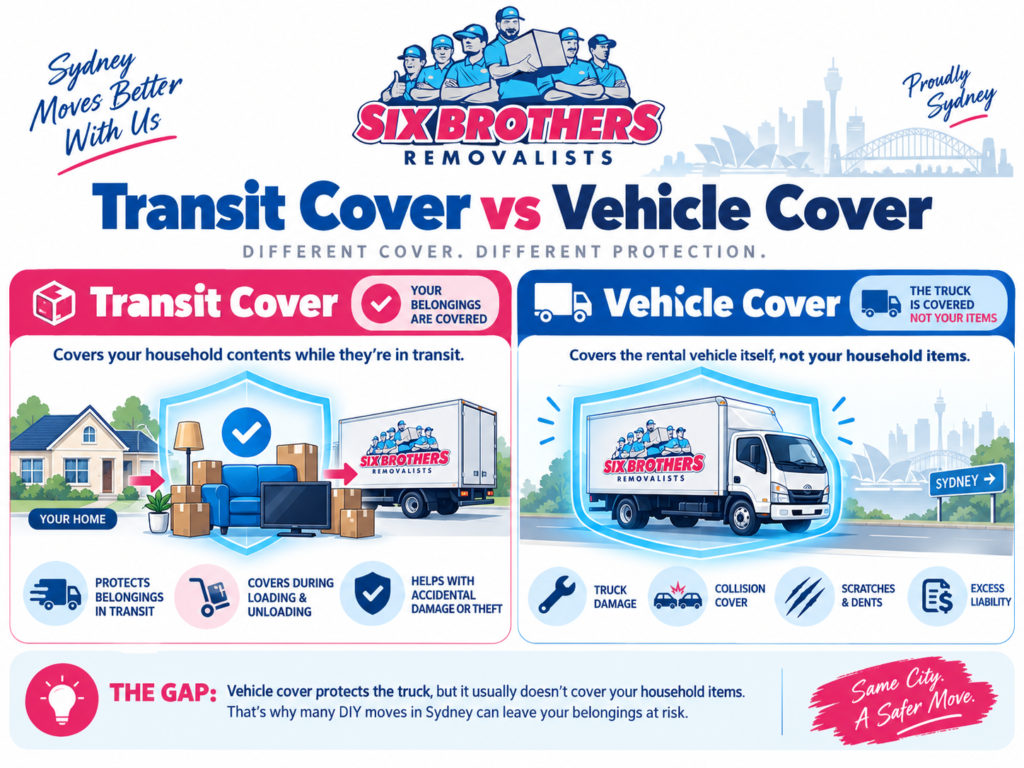
Ask the hire company whether any cover applies to household goods. Do not mistake reduced vehicle excess for moving insurance Australia. Check insurance for moving furniture separately.
Rental Truck Excess
An excess is the amount you may pay towards a covered claim. The amount can change by vehicle or driver. Compare it with the excess on any cargo policy.
Overhead Damage
A low awning or car park can damage the truck roof. Hire agreements may apply special exclusions or excesses. Measure the vehicle height and inspect access before driving.
Underbody Damage
Steep driveways and loading areas can damage steps or the underside. Ask the rental provider whether its damage waiver covers this. Photograph the vehicle before departure and return.
Water Damage
Rain can reach boxes through a poorly closed rear door. Ask whether the rental company covers the truck only. Keep belongings off the floor and wrap water-sensitive items.
The Temporary Storage Insurance Gap
Storage creates a separate period between houses. Ordinary contents, transit and storage policies may divide responsibility differently. Record where every box stays and for how long.
Self-Storage Cover
Self-storage insurance Australia may require a separate policy or approved facility cover. Ask about theft, water, fire, mould and item-value limits. Note exclusions for cash, jewellery and business stock.
Overnight Truck Storage
A locked truck parked outside your new home is not necessarily insured storage. Check your transit policy’s overnight conditions. A two-day house move needs cover for both days and the gap between them.
Garage Storage
A friend’s garage is not automatically part of your insured address. Ask both insurers what happens to your possessions there. Keep expensive electronics and documents in a secure location.
Storage Time Limits
Ask when temporary storage benefits start and expire. Some policies require an agreed facility or a maximum duration. Extend protection before your settlement or renovation dates change.
Proving a $10K+ Moving Insurance Claim
Good evidence helps the insurer assess what happened and what items were affected. It does not guarantee a payout. Start collecting records while everything is intact.
Pre-Move Inventory
List major furniture, appliances, electronics and high-value collections. Give each carton a number. A DIY moving Sydney three-bedroom house plan becomes easier when every valuable item has a recorded destination.
Condition Photos
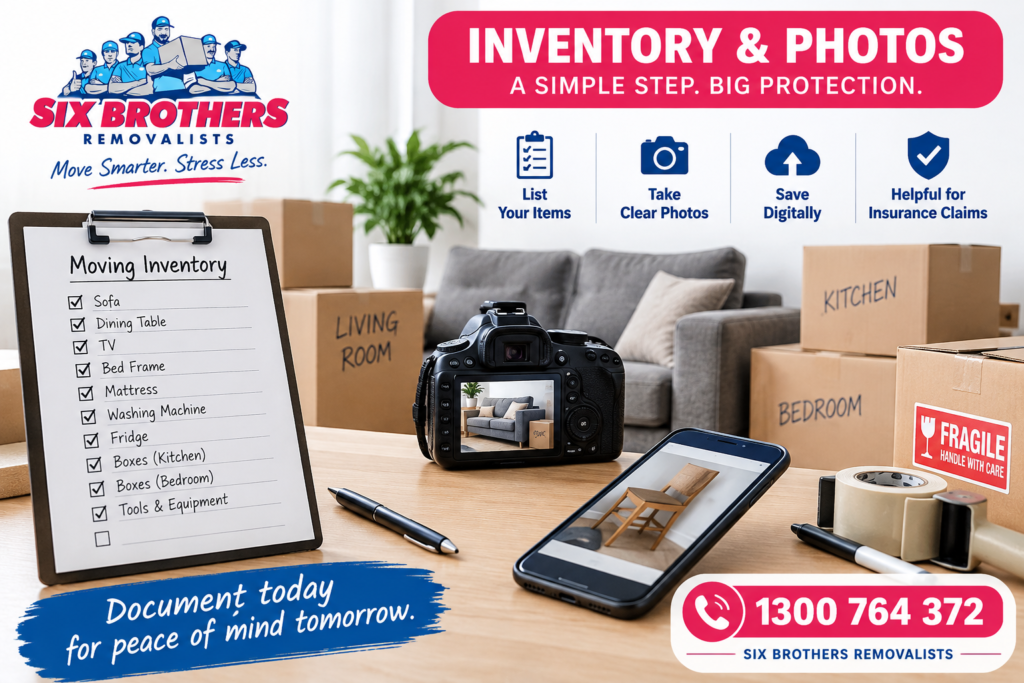
Photograph furniture corners, screens, serial labels and existing scratches. Take wider room photos before packing. Use clear dates and keep original files.
Receipts and Serial Numbers
Keep purchase receipts, valuations and serial numbers for high-value goods. Insurers may use them to assess ownership and value. Store digital copies outside the moving boxes.
Incident Evidence
Record the time, location, damaged item and people present. Photograph packaging before throwing it away. Report theft to police and request an incident reference when appropriate.
Claim Time Limits
Policies can set reporting duties and evidence requirements. Contact your insurer promptly after an incident. Ask for its claims process rather than relying on a generic online deadline.
How to Protect Yourself Before Starting
Protecting yourself begins with three written answers. What is insured? During which parts of the move? Who handles each claim? Work through these checks before paying for the truck.
Call your insurer first
Tell your insurer about both addresses, move dates, DIY loading and overnight stops. Mention temporary storage and any renovation work. Request a written answer for each cover gap.
Transition policies if required
Check when the old address stops and the new address starts. Ask about overlapping cover, portable valuables and transit. Compare exclusions before cancelling anything.
Verify professional licenses
Check NSW licences for electrical and plumbing work. Ask removalist companies about insurance certificates and actual policy benefits. Search queries like removalists near me cannot verify anyone’s cover.
Leave Specialist Tasks Alone
Move cartons if you can do so safely. Leave wiring, gas, plumbing and structural changes to qualified people. A cheap removalists quote cannot replace suitable insurance or safe handling.
Check Exempt Development Rules
Ask your council whether planned works need approval. Confirm the scope before stripping walls or altering plumbing. Keep building paperwork separate from moving insurance documents.
FAQs
Do removalists have insurance?
Many carry business policies, but their scope varies. Ask for evidence and check whether customer goods are insured.
Are removalists liable for damage?
Liability depends on the circumstances, contract and applicable law. Do not assume every breakage is insured.
Does home insurance cover moving house?
Some policies include moving benefits. Ask about loading, transit, unloading and time limits.
Will rental truck insurance pay for damaged furniture?
Vehicle damage cover does not automatically insure cargo. Check the rental terms and a separate goods policy.
Does moving insurance cover self-packed boxes?
Cover varies by insurer and policy. Ask about owner-packed cartons, fragile goods and proof of packing.
Is a vacant house uninsured after 60 days?
Not automatically. Tell your insurer the vacancy dates and request its specific conditions.
Can storage insurance cover a friend’s garage?
Only if the policy covers that location and circumstances. Ask before moving anything there.
Do I need special cover for renovations before moving?
Possibly. Disclose the scope, value and duration before work starts.
For a written moving plan, compare removalist rates and ask what handling services include. Insurance availability needs a separate, clear answer.
Discuss your moving dates with Six Brothers Removalists. Request a free quote or call 1300 764 372. Ask about transport, packing, storage and insurance before choosing your service.